


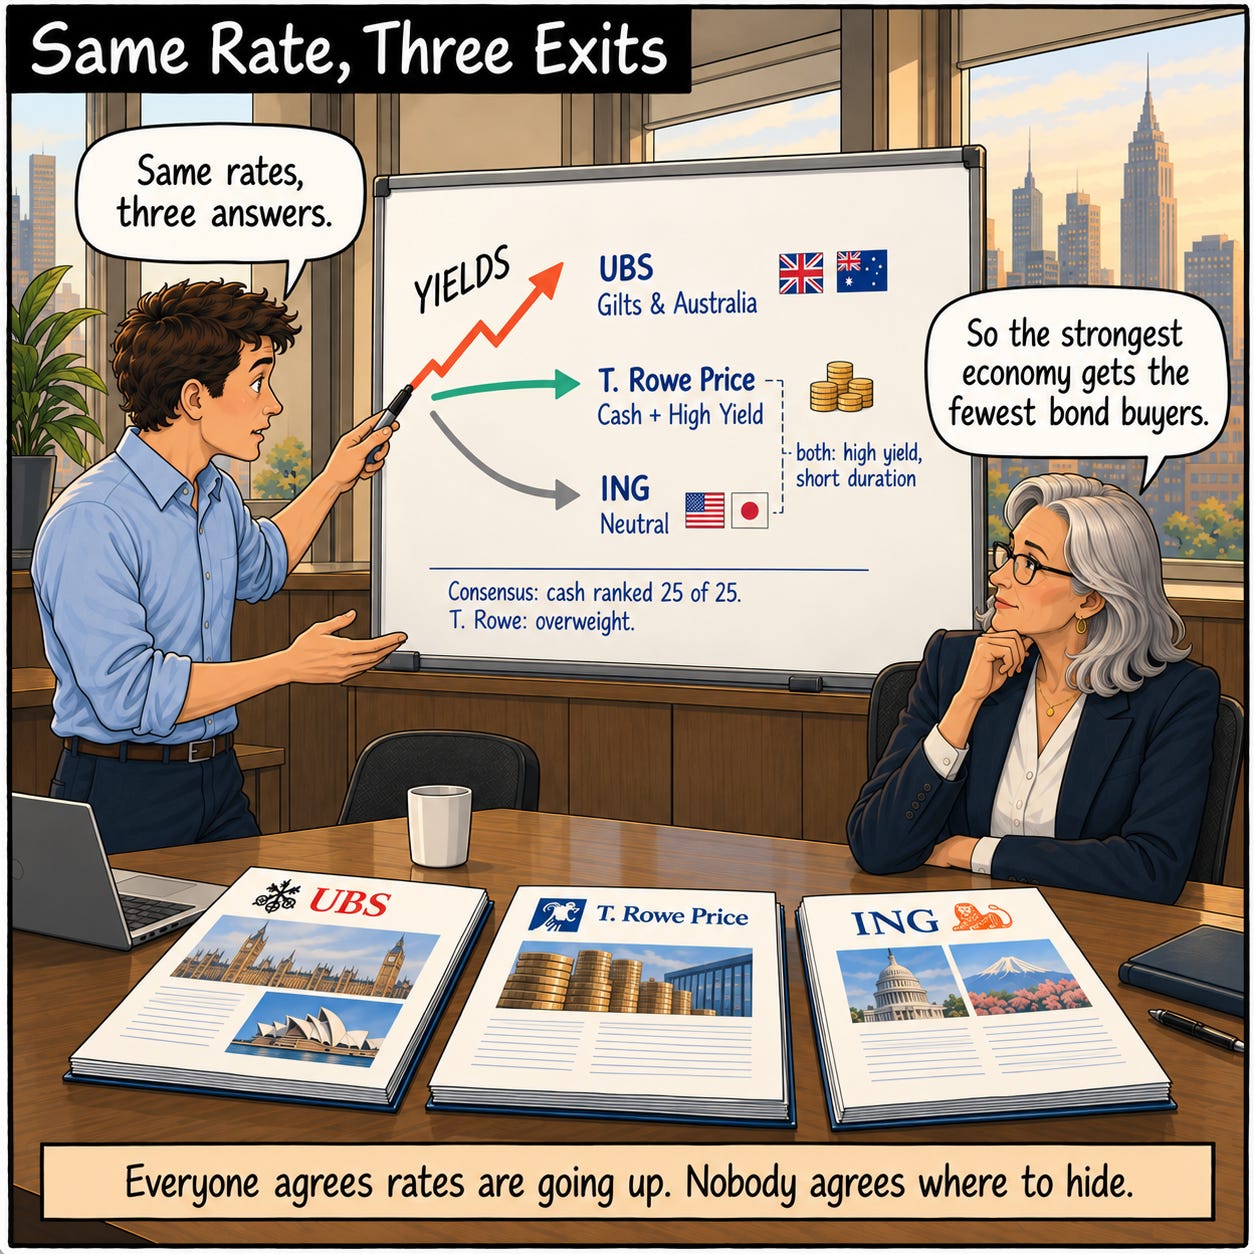
One winner and two finalists of the Asset Allocation Awards 2026 interpret this week’s rising interest rates in the same way but draw three different conclusions. UBS Asset Management views higher bond yields as a return to normal and is increasing its allocation to government bonds. T. Rowe Price combines cash with high-yield bonds, and focusing on HY short durations. ING Investment Office deviates somewhat from the consensus regarding equities: neutral where the consensus is overweight...
House View: UBS Asset Management
UBS Asset Management, a finalist for the Fixed Income Award and the Overall Award, has raised its recommendation for global government bonds from “neutral” to “overweight”: “We prefer to buy global duration on price dips. U.S. government bonds, however, remain at ‘neutral.” UBS buys duration where growth is most vulnerable, not in the strongest economy.
Macro Quarterly Q4 2026, Bonds: Normal for Longer, September 2026↗
House View: T. Rowe Price
T. Rowe Price, a finalist for the Equities Regional Award and the Overall Award, largely follows the consensus when it comes to equity regions; the difference lies in fixed-income securities. The company is cautious regarding duration and combines two positions where the consensus is underweight: cash and high yield. Cash is overweight, reflecting a negative view on government bonds: “The yield on cash remains reasonably attractive.” High yield is overweight due to healthy fundamentals with a focus on short duration.
Global Asset Allocation: The view from Europe, September 2026↗
House View: ING Investment Office
ING Investment Office, winner of the Equities Regional Award and, with 11 nominations over the past 11 years, a highly successful investor, takes a more cautious stance than the consensus. It is neutral on equities, North America, and Japan, where the consensus maintains an overweight position. The monthly report does not address this on a region-by-region basis. However, it does explain the reason for the neutral stance on equities in general: the equity risk premium is at “the lowest level in more than twenty years” (translated from Dutch). This asset allocation team has shown in the past that a neutral stance does not necessarily have to turn out badly.
Maandbericht Beleggen Oktober 2026↗
What this means for the consensus
Nevertheless, T. Rowe Price and ING Investment Office see one way out: both are overweight in high yield based on the same argument, namely “Short Duration High Yield.” The consensus is underweight High Yield and the asset class is ranked 22nd out of 25 asset classes. That is an early signal. As for government bonds, UBS is ahead of the consensus, which is neutral with only 22% of its recommendations at overweight.