


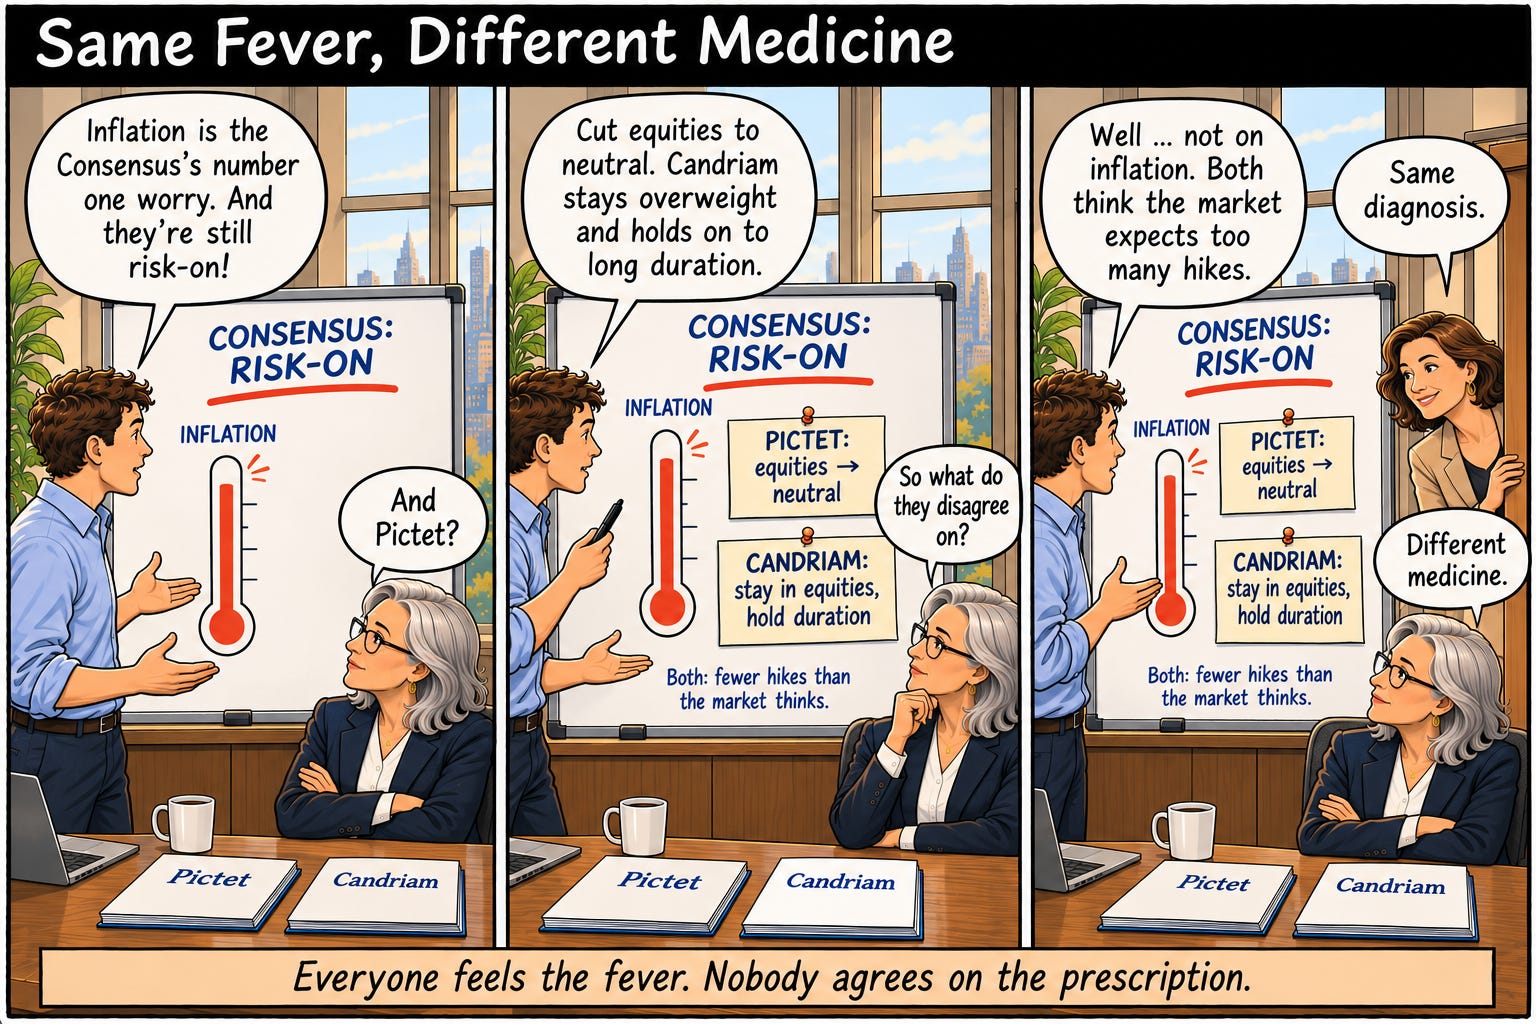
November has barely begun, and two finalists of the 2026 Asset Allocation Awards have already published the month’s first updates. The Consensus of 1 November remains risk-on: for the first time, inflation is the main concern, and asset managers are playing it through equities and commodities. Pictet Asset Management and Candriam both expect fewer rate hikes than the market. Yet they reach different conclusions: Pictet cuts equities to neutral, while Candriam stays in equities and keeps long duration in bonds.
House View: Pictet Asset Management
Pictet Asset Management, finalist for the Sectors Award, cuts equities as an asset class from overweight to neutral: “The mix of risks favours a neutral allocation across global equities, bonds and cash.” The reason is not inflation, which Pictet expects to peak in the US early next year, but tighter liquidity and rising borrowing costs. Financials also move to neutral: after Utilities and Industrials, that is already the third Consensus favourite in three months.
Barometer: Cutting back on equities as financial conditions offer less support, November 2026↗
House View: Candriam
Candriam, finalist for the Sectors Award and the Fixed Income Award, sees the inflation too: euro area inflation expectations are at their highest level since 2023. Still, its central scenario assumes “limited additional tightening”. Candriam stays slightly overweight equities and has held long duration in core European government bonds since September. Inflation fears, yes. Many more rate hikes, no.
Coffee Break: The Midterm test, November 2026↗
What It Means for the Consensus
With equities ranked second of the 25 asset classes we track (71% overweight), the Consensus is clearly risk-on; Pictet is moving away from that. Candriam stays overweight equities, but goes against the Consensus on government bonds, which it holds underweight (rank 21). Both expect fewer rate hikes than the market, but they are not moving together. So this is not yet an early signal.